Select Water’s $700 million Pilot deal expands Permian water infrastructure push
Select Water Solutions, Inc.
other
Select Water Solutions Announces Agreement to Acquire Pilot Water Solutions
U.S. Securities and Exchange Commission
government
Form 8-K - Select Water Solutions, Inc.
U.S. Securities and Exchange Commission
government
Membership Interest Purchase Agreement, dated as of September 24, 2026
$700M Deal
Select agreed to buy Pilot Water for $600 million in cash and $100 million of stock, with up to $15 million of additional earnout consideration.
Contracted Scale
Pilot brings about 480,000 barrels per day of minimum volume commitments and 306,000 dedicated acres under long-term agreements.
Infrastructure Pivot
Select expects Water Infrastructure to represent about 70% of pro forma profitability by 2027 after the acquisition.
Select Water Solutions said it agreed to acquire Pilot Water Solutions for $700 million in upfront consideration, a deal that would expand Select’s contracted water midstream platform in the Delaware Basin and accelerate its shift toward infrastructure-like cash flows.1
The transaction, announced September 24, includes $600 million in cash and $100 million of Select Class A common stock, plus up to $15 million in contingent cash tied to operational milestones.1 Select expects the acquisition to close in the fourth quarter of 2026, subject to customary conditions and regulatory approvals, including clearance under the Hart-Scott-Rodino Act.2
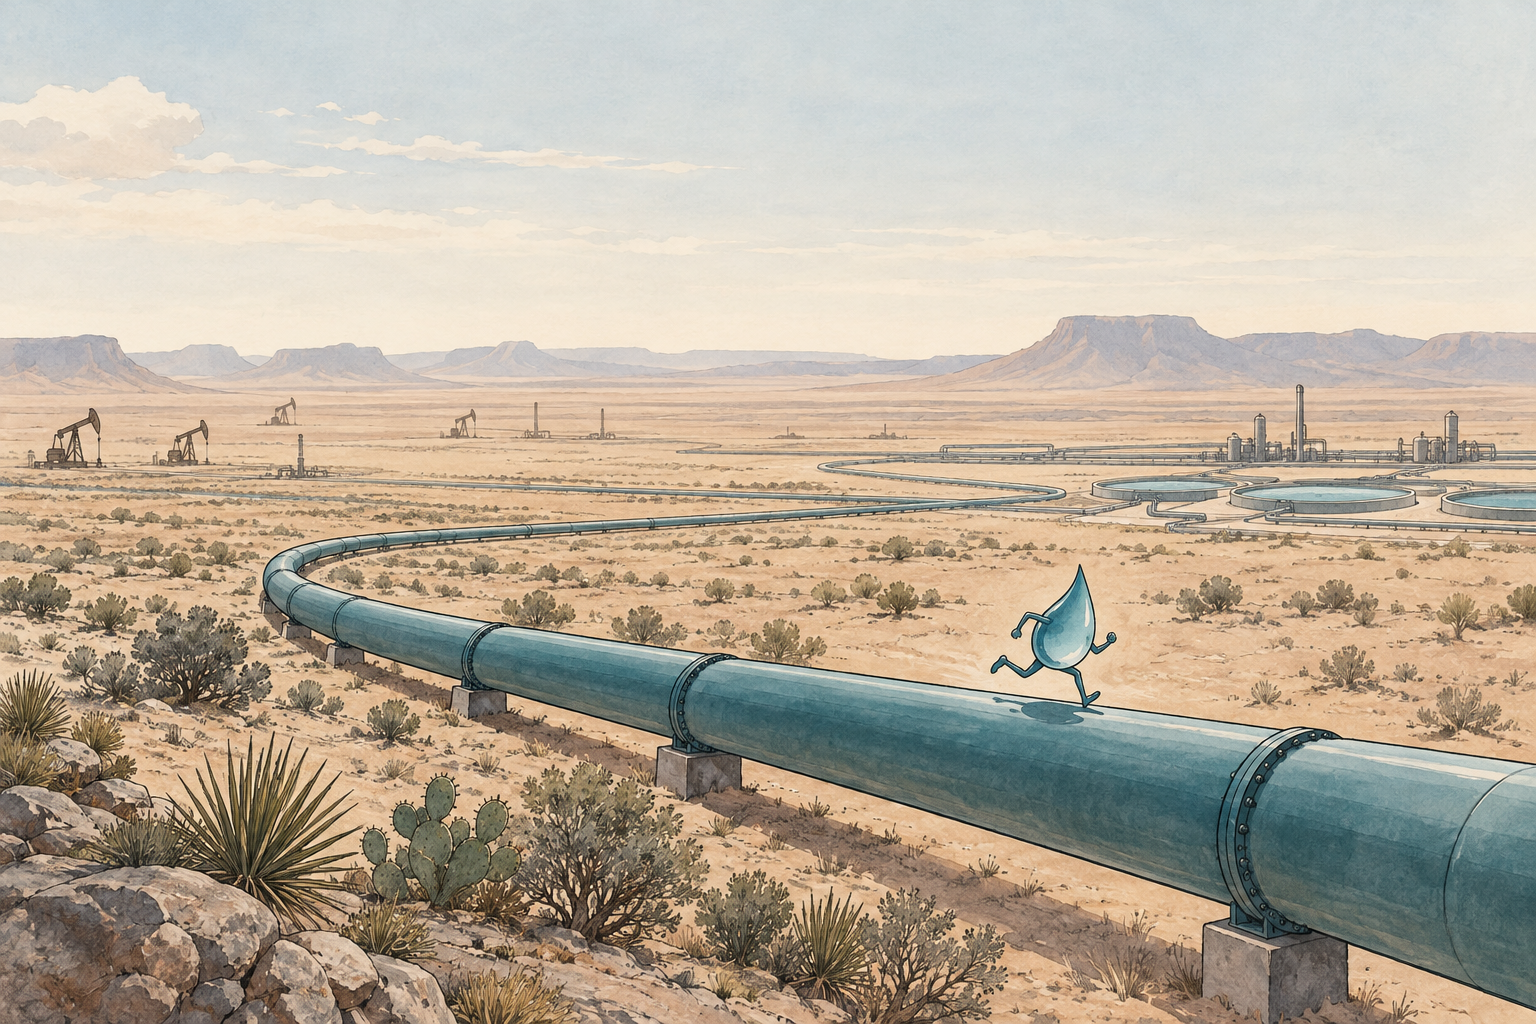
The deal is significant beyond its headline value. It shows how produced-water management is becoming a core Permian infrastructure business. Water volumes tied to shale production require pipelines, storage, recycling capacity, disposal permits and long-term producer commitments. Those features increasingly resemble midstream oil and gas infrastructure, not short-cycle oilfield services.
Pilot Water operates primarily in the Delaware Basin, one of the most active oil and gas producing regions in the United States. Its platform includes about 2.7 million barrels per day of active permitted disposal capacity, another 0.9 million barrels per day of undeveloped permitted disposal capacity and more than 700 miles of pipeline infrastructure.1
Select said more than 80% of Pilot Water’s annual revenue is backed by long-term contracts with an average remaining tenor of more than seven years. Those contracts include about 480,000 barrels per day of minimum volume commitments and 306,000 dedicated acres.1
That contract base is central to the strategy. Minimum volume commitments and acreage dedications give a water midstream operator better visibility into future volumes and revenue, reducing exposure to spot-market swings in completion activity.
Select said Pilot Water’s produced-water volumes are expected to rise from about 850,000 barrels per day in the first half of 2026 to roughly 1 million barrels per day in 2027, helped by a new 175,000-barrel-per-day MVC-based contract.1
Produced water has historically been treated as a support service for oil and gas operators: collect the water that flows back from wells, transport it, dispose of it or recycle it. In the Permian, the scale of production has changed the economics. Handling produced water now requires capital-intensive networks that can move large, steady volumes across multiple operators and outlets.
Select’s acquisition rationale reflects that shift. The company said combining Pilot’s disposal footprint with Select’s recycling network would create an integrated platform designed to handle the full lifecycle of produced and treated produced water.4
The combined water infrastructure platform is expected to include 3.8 million barrels per day of recycling capacity, 4.8 million barrels per day of active and undeveloped permitted disposal capacity, more than 1,600 miles of pipelines and about 57 million barrels of storage capacity.1
The investor presentation filed with the SEC framed the acquisition as a way to expand fee-based, production-linked cash flows. Select said the combined company would have about 605,000 barrels per day of MVC volumes and 3.6 million acres under dedication or right-of-first-refusal dedication, with a weighted average remaining tenor of about nine years.5
For energy infrastructure investors, those metrics matter because they are closer to midstream-style indicators than traditional oilfield service measures. Pipeline miles, permitted disposal capacity, dedicated acreage, contract tenor and MVC volumes point to the durability of future cash flows.
Pilot Water is expected to generate $100 million to $110 million of adjusted EBITDA in 2026 and $120 million to $130 million in 2027, before $10 million to $15 million of targeted annual cost synergies that Select expects to capture over the next 12 to 18 months.1
Select said the transaction should push its Water Infrastructure segment to about 70% of pro forma gross profit before depreciation and amortization by 2027.1 In its investor materials, the company said the deal accelerates its evolution into a leading water midstream company and increases its exposure to long-term, production-weighted contracts.5
The consideration structure and financing plan also show the strategic scale of the move. Select’s SEC filing identifies the sellers as Pilot OFS Holdings LLC and Minerva Infrastructure IA LLC, with Pilot Travel Centers LLC party to the agreement for limited purposes.3 The filing also states that Select entered into debt commitment letters with financing sources sufficient to consummate the acquisition.2
Select said it expects to maintain pro forma net leverage below 2.0 times at closing.1
The acquisition fits a broader pattern of consolidation in Delaware Basin water midstream. As produced-water volumes increase, larger operators can gain advantages by connecting systems, balancing water across a wider footprint, improving disposal utilization and routing more barrels toward recycling where economics and logistics support it.
Dealroom described the transaction as a sign of continued Delaware Basin water-midstream consolidation, with operators building scale to capture rising produced-water volumes tied to drilling and production.7 Investing.com reported that Select shares rose 14.4% in after-hours trading following the announcement, citing the market’s positive reaction to the infrastructure-led strategy and expected EBITDA contribution.6
The response reflects why water assets are attracting attention from energy services and infrastructure investors. Produced-water systems sit directly behind oil and gas production. They are needed whether the next barrel is drilled aggressively or development slows. Long-term contracts and acreage dedications can make the revenue stream more resilient than many activity-driven service lines.
For Select, Pilot Water adds disposal capacity, pipeline density and contracted Delaware Basin volumes that complement its existing recycling business. For the broader sector, the deal underscores a re-rating of water handling from a necessary cost center to strategic infrastructure.
The economics of Permian development increasingly depend on reliable water logistics. Operators need flow assurance for produced water, access to disposal capacity, recycling options and the ability to reduce freshwater demand where possible. Companies that control integrated water networks can capture more value across that chain.
If completed, the Pilot acquisition would make Select one of the more scaled public platforms pursuing that model: less a short-cycle oilfield services provider and more a contracted water midstream operator with infrastructure-style assets in the basin where water volumes are most consequential.

H&M’s latest results show a retailer improving margins but still struggling to reignite sales, even as the Persson family’s rising stake fuels take-private speculation. The strategic question is whether quarterly scrutiny is limiting the deeper supply-chain, store and digital changes H&M needs to compete with Inditex, Shein and other faster rivals.

A BlackRock- and IFM-backed bid for Stack Infrastructure’s Asia-Pacific portfolio underscores how AI capacity is being financed as long-duration infrastructure, not simply technology growth. The shift is drawing pension, sovereign, private credit and bank capital into assets whose value increasingly depends on power access, contracted demand and construction execution.

Tata Sons’ rejection of Tata Trusts’ objections to N. Chandrasekaran’s reappointment has turned a succession dispute into a broader test of power inside the Tata holding-company structure. The outcome could shape how quickly the group’s board can act on leadership, capital allocation and other strategic decisions when its controlling shareholder is divided.

Oasis Management’s 7.4% stake and proxy push at Vail Resorts is not just a referendum on share performance. The campaign is shaping into a broader test of whether centralized resort ownership, Epic Pass economics and local operating priorities still work for guests, mountain communities and investors.
Produced water
Water that comes to the surface during oil and gas production. It must be gathered, treated, recycled, reused or disposed of safely.
Minimum volume commitment
A contract provision requiring a customer to pay for a minimum level of throughput, which can make revenue more predictable for infrastructure owners.
Water midstream
Infrastructure that gathers, transports, stores, recycles or disposes of water associated with oil and gas production, similar in concept to oil and gas midstream systems.
Hart-Scott-Rodino Act
A U.S. antitrust law requiring certain large mergers and acquisitions to be reported to regulators before closing.
Comments