Humana’s $2.8B CenterWell Deal Reframes Primary Care as Infrastructure
Humana
other
Humana Announces New Strategic Joint Venture with BlackRock to Manage CenterWell Senior Primary Care Clinics
Humana / U.S. Securities and Exchange Commission
government
Humana Inc. Form 8-K Current Report
U.S. Securities and Exchange Commission
government
Humana Announces New Strategic Joint Venture with BlackRock to Manage CenterWell Senior Primary Care Clinics — Exhibit 99.1
$2.8B stake
BlackRock’s HPS Investment Partners will replace WCAS in a CenterWell joint venture tied to an equity stake valued at about $2.8 billion.
Nearly 150 clinics
The joint venture covers nearly 150 CenterWell Senior Primary Care clinics while CenterWell remains responsible for operations.
Capital strategy
Humana is using outside capital to reduce balance-sheet pressure while preserving operating control of a strategic care-delivery network.
Humana is replacing WCAS with BlackRock’s HPS Investment Partners as the outside capital partner in a joint venture covering nearly 150 CenterWell Senior Primary Care clinics. The transaction values WCAS’s equity stake at approximately $2.8 billion.13
Announced October 13, the deal keeps CenterWell in charge of clinic operations while shifting majority ownership of the venture to BlackRock-affiliated capital. The structure positions Humana to keep expanding care delivery without carrying the full asset burden on its own balance sheet.13
The transaction is expected to close in the fourth quarter of 2026 and does not change Humana’s 2026 guidance, according to market reporting on the announcement.9 For healthcare business leaders, the significance is less the sponsor swap than the model it reinforces: insurers with large care-delivery ambitions may increasingly treat primary-care networks as capital-intensive infrastructure platforms, pairing payer strategy and operating control with third-party capital.
Under the new structure, HPS Investment Partners will replace Welsh, Carson, Anderson & Stowe as Humana’s joint-venture partner. BlackRock will hold a majority stake in the venture, while CenterWell will continue managing clinic operations.13 Adviser-side confirmation from Latham & Watkins also identifies BlackRock and HPS as the represented parties in the new strategic joint venture with Humana.4
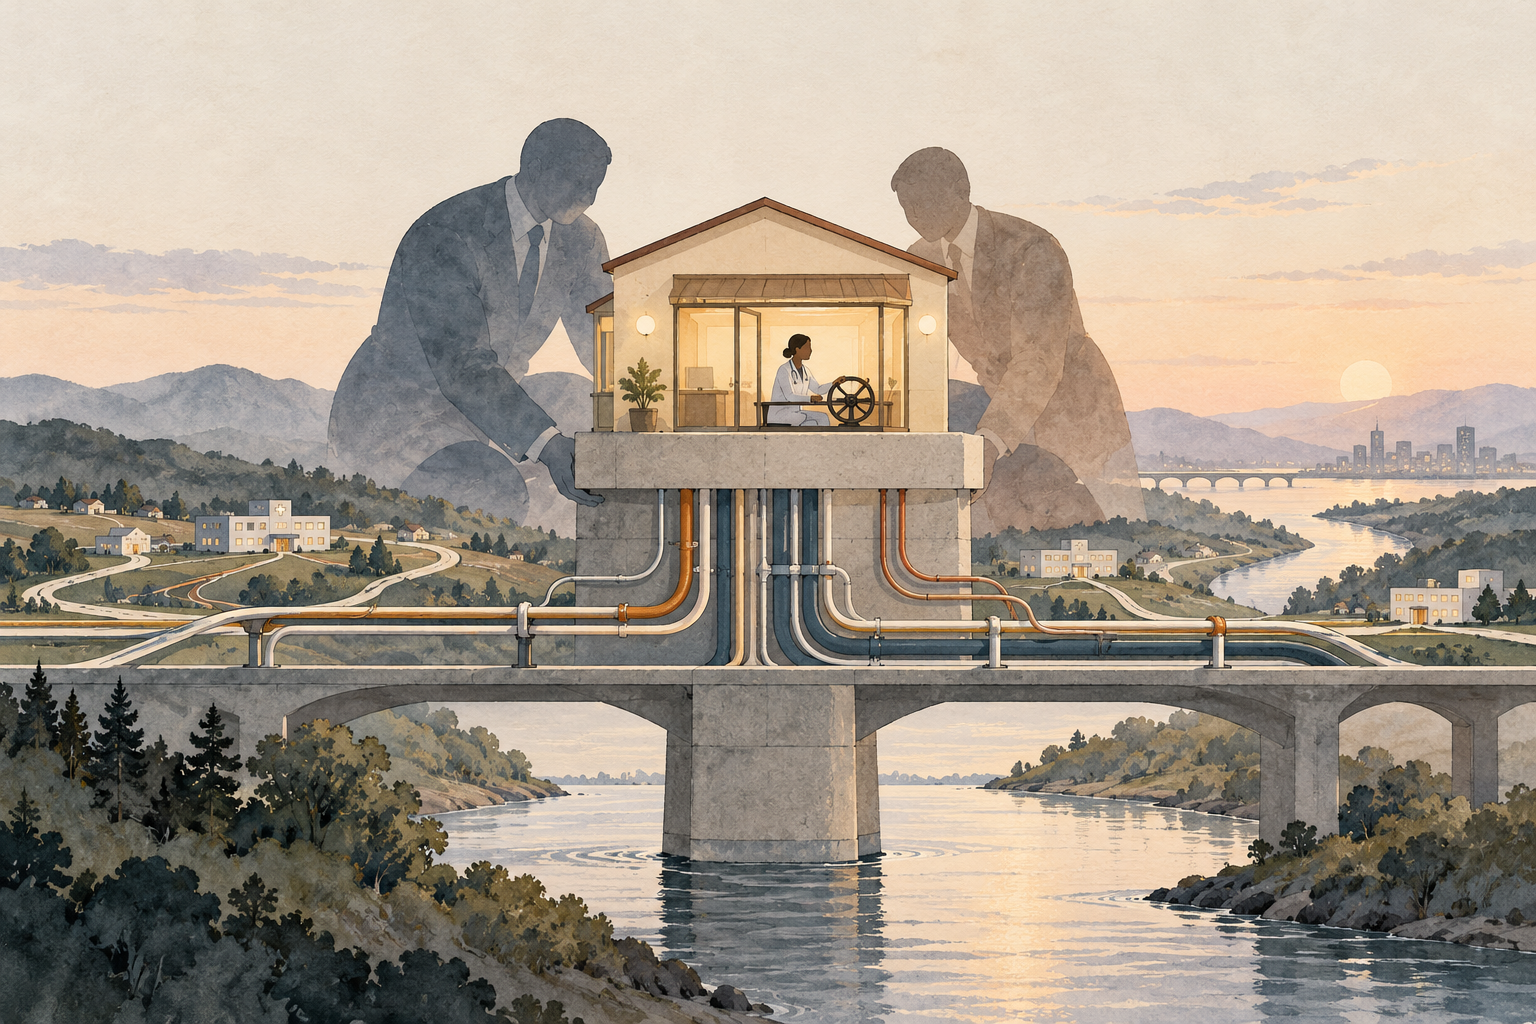
That division of roles is central to the strategic logic. Humana is not exiting primary care delivery. It is retaining the clinic operating relationship, the clinical model and the strategic alignment with its Medicare Advantage business, while bringing in a capital partner better suited to finance a growing physical-care platform.57
The formal securities filing adds another balance-sheet element: the deal removes the prior put option associated with the WCAS arrangement, is expected to reduce liabilities and gives CenterWell future purchase options tied to the venture.2 In practical terms, Humana is reducing a financing overhang while preserving a path to regain ownership optionality later.
Primary care has become a strategic control point for Medicare Advantage insurers. Clinics can help manage risk, coordinate care, influence utilization and create more durable relationships with seniors. But building and owning clinics is capital intensive. Facilities, physicians, care teams, technology and local market expansion all require long-term investment before returns fully materialize.
The BlackRock-HPS deal points to a middle path. Humana can keep the strategic benefits of operating CenterWell clinics while funding growth through a partner that views the assets through an infrastructure and private-credit lens. Healthcare Dive framed the transaction around balance-sheet flexibility and growth capital, noting BlackRock’s majority stake in nearly 150 clinics.5 Fierce Healthcare similarly highlighted Humana’s goal of unlocking growth capital while maintaining CenterWell operations.7
That model may appeal to other payers and risk-bearing providers. Rather than owning every clinic outright, insurers can separate the operating platform from the asset-capital layer. The payer or care-delivery company keeps clinical and strategic control; the financial partner supplies long-duration capital and absorbs part of the ownership burden.
STAT characterized the deal as Humana swapping private-equity sponsors in a Medicare Advantage clinic network, with capital available for operations, new clinics and acquisitions.6 That captures the transaction’s immediate mechanics, but the broader implication is that primary-care networks are being financed more like scalable platforms than conventional provider subsidiaries.
The shift also reflects a maturing market. In earlier stages, payer-owned primary care was often discussed mainly as vertical integration: the insurer buys or builds the clinics, aligns incentives and captures more of the value chain. The Humana transaction suggests a more modular approach. Ownership, operations and financing can be separated and recombined as the network grows.
For Humana, that matters because CenterWell is both a care-delivery asset and a Medicare Advantage strategy. Keeping CenterWell as operator allows the company to preserve clinical continuity and alignment with its broader senior-care model, while the joint venture helps finance the clinics at what the company filing describes as a lower cost of capital.2
The deal also shows how capital structure is becoming part of healthcare strategy. Louisville Business First, covering the announcement from Humana’s home market, emphasized the liability-reduction and cost-of-capital rationale behind the new partnership.8 Those are not merely financial details. They can determine how quickly a clinic network can enter new markets, acquire practices or withstand pressure in Medicare Advantage margins.
For insurers, the trade-off is clear. Fully owning clinics offers maximum economics and control, but it ties up capital and exposes the company to real estate, labor and operating-cost risk. Joint ventures reduce that burden, but they require governance discipline and alignment with a financial partner whose return expectations may differ from the insurer’s care-management goals.
Humana’s structure attempts to preserve the part that matters most strategically: operating control. If CenterWell continues managing the clinics, Humana can keep directing the care model, patient experience and clinical integration while using outside capital to support scale.13
The first question is whether the transaction closes as expected in the fourth quarter of 2026 and whether the liability reduction outlined in Humana’s filing materializes as planned.29 The second is whether Humana uses the new structure mainly to stabilize its balance sheet or to accelerate clinic expansion, acquisitions and market entry.
The third is whether competitors follow. Large insurers and risk-bearing provider groups face the same tension: primary care is strategically valuable, but building networks requires substantial capital. If Humana’s BlackRock-HPS partnership delivers lower financing costs without weakening operating control, similar structures could become more common across payer-owned and value-based care platforms.
The message for healthcare business leaders is straightforward. Primary care is no longer just an operating capability for insurers. It is becoming an investable infrastructure layer — one that can be owned, financed and scaled through structures that look increasingly like the rest of the alternative-asset market.

Mexico’s antitrust authority is expected to clear the planned merger of Viva Aerobus and Volaris by the end of 2026, Reuters reported, likely creating the country’s largest airline group. Regulators are expected to attach operating commitments aimed at keeping fares low, limiting layoffs and preserving network coverage.

Apple supplier Jabil and Adani Enterprises have signed a non-binding framework for a proposed equal joint venture to make AI and data-center equipment in India. The plan links global contract-manufacturing expertise with Indian infrastructure capacity, but its success will depend on whether India can build a deeper supplier base for high-value data-center systems.

Workday’s agreement to acquire C1.ai signals a broader push to make identity governance, permissions and audit trails foundational to how companies deploy AI agents across HR, finance and IT. The bet is that as agents proliferate, the system that controls what they can access and prove becomes as strategic as the agents themselves.

LSEG’s confirmed talks to buy Permira-owned Octus for about $3.5 billion underscore a broader push by exchanges and financial-data groups into specialist subscription platforms. The potential deal would deepen LSEG’s fixed-income and private-markets data franchise, but it also raises execution and valuation questions under activist scrutiny.
Joint venture
A business structure in which two or more parties share ownership of an asset or operating platform, often to combine strategic control with outside capital.
Put option
A contractual right that can require one party to buy an ownership stake from another under defined terms; removing it can reduce future balance-sheet risk.
CenterWell Senior Primary Care
Humana’s senior-focused primary-care clinic business, which supports care delivery for older adults and aligns with the company’s Medicare strategy.
Infrastructure platform
An asset base financed for long-term, capital-intensive growth, such as clinics, facilities or networks that can support recurring operations over time.
Comments